MORTGAGE BROKING
Mortgage Broking in Craigieburn
Home Loans & Finance Solutions for Craigieburn
Craigieburn carries more construction lending than almost anywhere else Loan Point Solutions works, and construction finance is a different product with different failure modes. Across the Highlands, Aston and Mount Ridley estates and up through Mickleham and Kalkallo, buyers are settling land first and building second, which means progressive drawdowns, a fixed-price contract the lender has to accept, and an on-completion valuation that occasionally lands below the land price plus build cost. Those risks are manageable when they are identified before a building contract is signed and expensive afterwards. We review the contract, structure the staged funding and chase each progress draw so your builder is not waiting on a bank. Call 0485 011 020.
GET A FREE CONSULTATION
OUR STORY
Why Loan Point Solutions Started in Craigieburn
Loan Point Solutions was established with a simple idea: arranging finance should feel personal, straightforward and easier to understand. Craigieburn has grown into a large residential community, with established neighbourhoods alongside newer developments and expanding housing areas. The local property market includes houses, townhouses and units, giving buyers different options depending on their plans and circumstances. We wanted to build a mortgage brokerage that takes those differences into account rather than treating every application the same way. Whether you are buying your first home, moving into a larger property, refinancing or considering an investment, we take the time to understand your circumstances and compare suitable lending options. Today, we assist clients throughout Craigieburn, Melbourne and Australia-wide while keeping the personal approach that shaped Loan Point Solutions from the beginning.
SERVICES WE OFFER IN Craigieburn
What Lending in Craigieburn Actually Looks Like
Lending in Craigieburn can look quite different depending on the property and the borrower. The suburb includes established homes as well as newer houses, townhouses and units across different residential areas. For someone looking to purchase in Craigieburn, the appropriate loan can depend on factors such as income, deposit, existing commitments, property type and lender criteria. Some buyers may be purchasing an established family home, while others may be looking at a newer property, building a home or refinancing an existing loan. At Loan Point Solutions, we look at the circumstances behind each application before comparing suitable lending options. We help clients understand the requirements involved and work through the finance process without assuming one loan structure will suit everyone.
Why choose us in Craigieburn
Why Craigieburn Locals Use Loan Point Solutions
Choosing a mortgage broker can be about having someone who takes the time to understand what you are trying to achieve. At Loan Point Solutions, we start by understanding your circumstances before considering suitable lending options. Craigieburn has a mix of established and newer neighbourhoods, including areas such as Highlands, Aston and Craigieburn North, while nearby buyers may also compare properties in Roxburgh Park, Greenvale and Mickleham. Different property types and stages of development can mean different lending considerations, so understanding your position before making a decision can be important. We help clients compare suitable options and understand differences between lenders, loan structures, rates, features and requirements. Our focus is on clear communication and practical assistance throughout the lending process.
SERVICES WE OFFER IN Craigieburn
The Streets and Pockets We Work Across in Craigieburn
Craigieburn has a number of recognisable residential pockets connected by major local roads and community facilities. Aitken Boulevard, Grand Boulevard, Craigieburn Road, Mickleham Road and Mount Ridley Road are important routes through and around the suburb, while Highlands, Aston and Craigieburn North include established and newer residential neighbourhoods. The Craigieburn Town Centre area also sits around important local roads and community facilities. Whether you are purchasing a home in an established street, buying in a newer development, refinancing an existing property or considering an investment, Loan Point Solutions can assist with the finance side of the process. We consider the proposed property, your circumstances and relevant lender requirements before comparing suitable options. We also assist clients throughout Melbourne and Australia-wide.
Mortgage Broking Services we offer In Craigieburn
We help you find a home loan that is suited to your financial circumstances and long-term goals. We consider your income, deposit, existing commitments and borrowing capacity before comparing suitable lending options. With access to a broad range of lenders, we can compare interest rates, loan features and structures to help you make an informed decision. Whether you are purchasing your first home, upgrading or refinancing, we provide clear guidance throughout the lending process, from application through to settlement.
We help first home buyers understand their options, compare suitable lenders and find a home loan solution that fits their deposit, income and circumstances. Based in Melbourne, we serve Westmeadows and surrounding areas, as well as clients Australia-wide.
Whether you’re buying your first investment property, growing your portfolio or refinancing, we compare 30+ lenders to find a loan suited to your goals and circumstances. Based in Melbourne, we serve Westmeadows and surrounding areas, as well as clients Australia-wide.
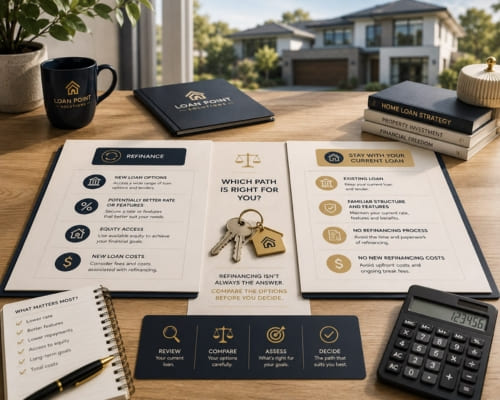
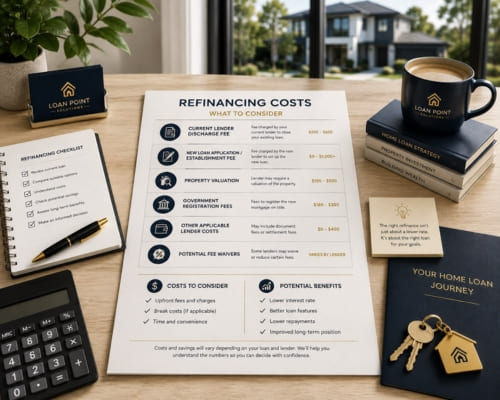
Whether you’re looking to review your current loan, access equity or consolidate eligible debts, we compare options from 30+ lenders to help you explore suitable refinancing options. Based in Melbourne, we assist clients across Melbourne and Australia-wide.
Whether you’re building your first home or an investment property, we compare construction loan options from 30+ lenders to find a solution suited to your circumstances. We consider your land, building contract, deposit and project costs. Based in Melbourne’s northern suburbs, we assist clients across Melbourne and Australia-wide.
Whether you’re purchasing commercial property, expanding your business or refinancing existing debt, we compare options from 30+ lenders to help find a loan suited to your circumstances and goals. Based in Melbourne, we assist businesses across Melbourne and Australia-wide.
Explore suitable SMSF property finance options from 30+ lenders, based on your fund structure, financial position and lending requirements. Based in Melbourne, we assist clients across Melbourne and Australia-wide.
Whether you’re purchasing a vehicle, equipment, machinery or other business assets, we compare asset finance options from 30+ lenders to help identify a solution suited to your circumstances. Based in Melbourne, we assist clients across Melbourne and Australia-wide.
Whether you’re starting, expanding or managing your business, we compare business loan options from 30+ lenders to help identify a solution suited to your circumstances. Based in Melbourne, we assist businesses across Melbourne and Australia-wide.
Mortgage Broking In Craigieburn
FREQUENTLY ASKED QUESTIONS
Everything you need to know about our Mortgage Broking In Craigieburn
What does a mortgage broker cost in Craigieburn?
It depends on how your income is structured, and in this suburb it usually is worth it. If you are on a flat salary with a large deposit, your own bank is a perfectly reasonable first stop. If any part of your income comes from shift allowances, penalty rates, overtime or a second job, which describes a large share of Westmeadows households working at the airport and through the freight corridor, then the lender you choose changes your borrowing figure substantially. One lender may count all of your shift loading, another only 80 per cent of it, and a third may want twelve months in the role first. Comparing that policy is the whole point of the exercise.
Should you look at my building contract before I sign it?
Somewhere between all of it and none of it, depending entirely on which lender assesses the file. The variables lenders apply are how long you have been in the role, whether the allowances are contractual or discretionary, whether your employer will confirm them as ongoing, and whether they appear consistently across two payslips or two years of group certificates. Shift and penalty loadings in essential and 24-hour operations, which covers most airport ground handling, freight and logistics work, are generally treated more favourably than discretionary overtime in an office role. We check the specific policy against your payslips before an application goes anywhere near a lender.
How do the progress payments actually work on a house-and-land package?
For a standard residential home loan or [refinance](/refinancing), nothing. The lender pays us a commission when the loan settles, typically around 0.65 per cent of the loan amount plus GST upfront and a smaller ongoing trail, and none of that is added to your rate or your balance. A fee-for-service applies only in specific circumstances, essentially commercial and complex business facilities rather than home lending, and you would be given the amount in writing before any work began. There is no charge for an initial conversation, a borrowing capacity assessment or a pre-approval that does not proceed.
What if the on-completion valuation is lower than my land price plus build cost?
Yes. Postcode 3049 covers Westmeadows and Attwood together, and in practice we work across the whole pocket bounded by the Tullamarine Freeway and the Western Ring Road, which takes in Gladstone Park, Jacana, Broadmeadows and Greenvale. These suburbs share a lending profile more than they differ, with similar employment patterns and comparable housing eras, so the same lender knowledge applies. If you are further out toward Roxburgh Park or Bulla, call 0485 011 020 and we will confirm, because we almost certainly still cover you.
Do you cover Mickleham, Kalkallo, Roxburgh Park and Greenvale?
That is the normal arrangement here rather than an exception. A significant proportion of Westmeadows clients work rosters that make a nine-to-five appointment impossible, so meetings happen in the evening, on weekends, or over a screen share where that is easier than travelling. We work from Gwilt Street in Westmeadows, so a local face-to-face meeting is straightforward, and documents can be signed digitally rather than requiring a trip. Tell us your roster and we will work around it.
How long from signing a build contract to moving in?
Allow two to four weeks for the finance approval, which takes slightly longer than a standard home loan because the lender also assesses the contract, plans and permits. The build itself is the long part, and a standard single-storey home commonly runs nine to fifteen months from slab to handover, with delays from weather, trade availability and material supply being routine rather than exceptional. Where the land has not yet titled, add that wait on top, since a build cannot start until the land settles. Budget for holding costs across the whole period, because most people are paying rent alongside the loan interest until handover.
TESTIMONIALS
What Craigieburn Homeowners Say About Us
Request A Free Quote
BUSINESS
SERVICES
SERVICE AREAS
OPERATING HOURS
Sun: 9:00am - 9:00pm
Mon: 9:00am - 9:00pm
Tue: 9:00am - 9:00pm
Wed: 9:00am - 9:00pm
Thu: 9:00am - 9:00pm
Fri: 9:00am - 9:00pm
Sat: 9:00am - 9:00pm
CRN: 580515
ABN: 72 699 469 228