MORTGAGE BROKING
Mortgage Broking in Essendon
Home Loans & Finance Solutions for Essendon
Essendon runs on larger loans than the suburbs north of it, and larger loans change which mistakes matter. Buyers here are typically upgraders moving into a period home off Keilor Road or Mt Alexander Road, or investors adding a second and third property, and the structural decisions taken on those files, particularly whether the lender cross-secures your existing home against the new purchase, determine whether you can keep buying afterwards. Professional households here also frequently qualify for lenders mortgage insurance waivers that go unclaimed. Loan Point Solutions structures Essendon lending with the next purchase in mind rather than just the current one, keeping securities standalone wherever the numbers allow. Call 0485 011 020.
GET A FREE CONSULTATION
OUR STORY
Why Loan Point Solutions Started in Essendon
Loan Point Solutions was established with a simple idea: arranging finance should feel personal, straightforward and easier to understand. Essendon is an established Melbourne suburb with a residential character, a mix of older homes and newer apartments, and a shopping and transport network. We wanted to build a mortgage brokerage that takes those differences into account rather than treating every application the same way. Whether you are buying your first home, moving to a larger property, refinancing or considering an investment, we take the time to understand your circumstances and compare suitable lending options. Our approach is about listening first, explaining the finance process clearly and helping clients understand what is involved. Today we assist clients throughout Essendon, Melbourne and Australia-wide while maintaining the personal approach that shaped our business.
SERVICES WE OFFER IN Essendon
What Lending in Essendon Actually Looks Like
Lending in Essendon can look quite different depending on the property and the borrower. The suburb has established family homes alongside townhouses, apartments and units, giving buyers different types of properties to consider. For someone looking to purchase in Essendon, the appropriate loan can depend on factors such as income, deposit, existing commitments, property type and lender criteria. Some buyers may be looking for an established home on a larger block, while others may prefer an apartment or townhouse closer to Mount Alexander Road and local transport. At Loan Point Solutions, we look at the circumstances behind each application before comparing suitable lending options. We help clients understand the requirements involved and work through the finance process without assuming that one loan structure or lender will suit everyone.
Why choose us in Essendon
Why Essendon Locals Use Loan Point Solutions
For Essendon locals, choosing a mortgage broker can be about having someone who takes the time to understand their circumstances rather than simply presenting a list of loans. At Loan Point Solutions, we start by understanding what you are looking to achieve before considering lending options. Essendon's established property market means buyers may be comparing different styles of homes, apartments and townhouses, while nearby areas such as Moonee Ponds, Strathmore, Aberfeldie and Essendon North can also form part of a wider property search. We help clients compare suitable options and understand differences between lenders, loan structures, rates, features and requirements. Whether you are purchasing, refinancing or considering an investment, our focus is on clear communication and practical assistance throughout the lending process, without assumptions about what will suit every borrower.
SERVICES WE OFFER IN Essendon
The Streets and Pockets We Work Across in Essendon
Essendon has several recognisable local pockets, from the Mount Alexander Road shopping and transport corridor through to established residential streets around Buckley Park and the Moonee Ponds Creek. Streets including Buckley Street, Fletcher Street, Keilor Road, Glass Street, Napier Street and Hoffmans Road connect different parts of the suburb and surrounding areas. The Essendon Station precinct is another important local area, with transport links and nearby shops and services. Whether you are purchasing an established home, considering an apartment or townhouse, refinancing an existing property or looking at an investment, Loan Point Solutions can assist with the finance side of the process. We consider the proposed property, your circumstances and relevant lender requirements before comparing suitable options, while assisting clients throughout Essendon, Melbourne and Australia-wide.
Mortgage Broking Services we offer In Essendon
We help you find a home loan that is suited to your financial circumstances and long-term goals. We consider your income, deposit, existing commitments and borrowing capacity before comparing suitable lending options. With access to a broad range of lenders, we can compare interest rates, loan features and structures to help you make an informed decision. Whether you are purchasing your first home, upgrading or refinancing, we provide clear guidance throughout the lending process, from application through to settlement.
We help first home buyers understand their options, compare suitable lenders and find a home loan solution that fits their deposit, income and circumstances. Based in Melbourne, we serve Westmeadows and surrounding areas, as well as clients Australia-wide.
Whether you’re buying your first investment property, growing your portfolio or refinancing, we compare 30+ lenders to find a loan suited to your goals and circumstances. Based in Melbourne, we serve Westmeadows and surrounding areas, as well as clients Australia-wide.
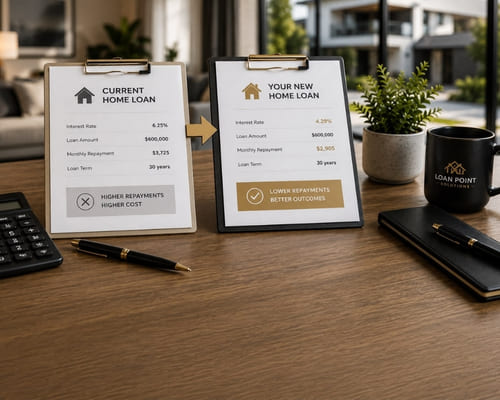
Whether you’re looking to review your current loan, access equity or consolidate eligible debts, we compare options from 30+ lenders to help you explore suitable refinancing options. Based in Melbourne, we assist clients across Melbourne and Australia-wide.
Whether you’re building your first home or an investment property, we compare construction loan options from 30+ lenders to find a solution suited to your circumstances. We consider your land, building contract, deposit and project costs. Based in Melbourne’s northern suburbs, we assist clients across Melbourne and Australia-wide.
Whether you’re purchasing commercial property, expanding your business or refinancing existing debt, we compare options from 30+ lenders to help find a loan suited to your circumstances and goals. Based in Melbourne, we assist businesses across Melbourne and Australia-wide.
Explore suitable SMSF property finance options from 30+ lenders, based on your fund structure, financial position and lending requirements. Based in Melbourne, we assist clients across Melbourne and Australia-wide.
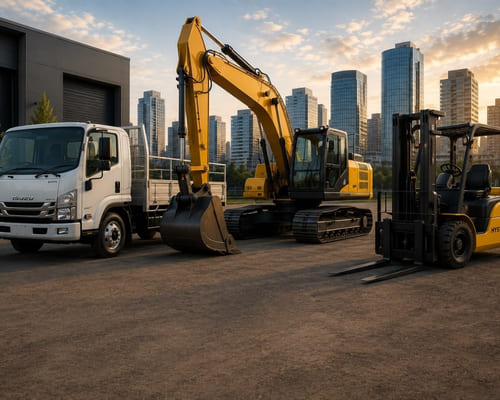
Whether you’re purchasing a vehicle, equipment, machinery or other business assets, we compare asset finance options from 30+ lenders to help identify a solution suited to your circumstances. Based in Melbourne, we assist clients across Melbourne and Australia-wide.
Whether you’re starting, expanding or managing your business, we compare business loan options from 30+ lenders to help identify a solution suited to your circumstances. Based in Melbourne, we assist businesses across Melbourne and Australia-wide.
Mortgage Broking In Essendon
FREQUENTLY ASKED QUESTIONS
Everything you need to know about our Mortgage Broking In Essendon
Is it worth paying a mortgage broker in Essendon?
You do not pay us on residential lending, so the question is really whether a broker adds anything over your own bank, and at Essendon loan sizes it usually does. On a larger loan, structure matters more than a small difference in rate. Whether your existing home is cross-secured against a new purchase, whether an interest-only period is set to expire at a bad time, and whether you qualify for a professional lenders mortgage insurance waiver are all decisions worth more over a decade than a marginal rate difference. A bank can only structure within its own product set; we compare several and explain the trade-offs.
How much does a mortgage broker cost in Essendon?
Nothing on standard residential lending, whether that is a purchase, a refinance or an [investment loan](/investment-loans). Our commission is paid by the lender at settlement, typically around 0.65 per cent of the loan amount plus GST upfront plus a smaller ongoing trail, and it does not affect your rate or your balance. Fees arise only on commercial and complex business facilities, where you would be told the amount in writing before any work began. Larger loan sizes do not attract a larger fee from us, because there is no fee.
I already own in Essendon and want to buy an investment. Should the lender hold both properties?
Usually not, and this is the single most consequential decision on these files. Cross-collateralisation, where one lender holds both properties as security for both loans, is convenient for the lender and restrictive for you. It complicates selling either property, because the lender must reassess the whole position and may require sale proceeds to reduce the remaining debt. It makes moving one loan elsewhere difficult without unwinding everything. And it concentrates your entire portfolio with a single lender, so one policy change affects all of it. We prefer a standalone structure with a separate equity release wherever the numbers permit, and if cross-securing genuinely is the only way a purchase works, you will be told that explicitly rather than have it happen quietly.
My income is high but my borrowing capacity came back lower than expected. Why?
High income and high borrowing capacity are not the same thing, and the gap is usually explained by four things. Credit card limits are assessed at the full limit regardless of the balance, so an unused $30,000 limit is treated as debt. Existing investment debt is assessed at a buffered rate, and some lenders assess other lenders' loans far more harshly than others. HECS-HELP repayments scale with income, so they bite hardest at exactly the incomes that feel comfortable. And private school fees, childcare and novated leases are all counted as commitments. Because lenders weight these differently, the same household can be assessed tens of thousands of dollars apart across two lenders.
Do you cover Aberfeldie, Strathmore, Niddrie and Moonee Ponds?
Yes, along with Essendon North, Airport West, Keilor East and Ascot Vale. These suburbs share Essendon's profile fairly closely, with substantial period housing, higher price points and a strong upgrader and investor market, though Moonee Ponds carries considerably more apartment stock which brings its own lender size and postcode rules. Essendon Fields is a distinct case, being largely commercial and business-park property rather than residential, and that work runs through our [commercial loans](/commercial-loans) side. Call 0485 011 020 with the address.
Can you help if I need to buy before I sell?
That is a bridging loan, and it is a common requirement among Essendon upgraders. A bridging facility funds the new purchase while your existing property is still on the market, with the combined debt referred to as peak debt, reducing to the end debt once the sale settles. Most lenders allow a bridging period of six to twelve months and will assess whether you could service the peak debt if the sale took longer than expected, which is the real constraint. Interest is typically capitalised during the bridging period rather than paid monthly. Not every lender offers bridging and terms differ substantially, so it needs the right lender chosen at the outset.
TESTIMONIALS
What Essendon Homeowners Say About Us
Request A Free Quote
BUSINESS
SERVICES
SERVICE AREAS
OPERATING HOURS
Sun: 9:00am - 9:00pm
Mon: 9:00am - 9:00pm
Tue: 9:00am - 9:00pm
Wed: 9:00am - 9:00pm
Thu: 9:00am - 9:00pm
Fri: 9:00am - 9:00pm
Sat: 9:00am - 9:00pm
CRN: 580515
ABN: 72 699 469 228