INVESTMENT LOANS
Build Your Property Portfolio With the Right Loan.
Smarter finance for your next property investment.
Whether you're buying your first investment property, growing your portfolio or refinancing, we compare 30+ lenders to find a loan suited to your goals and circumstances. Based in Melbourne, we serve Westmeadows and surrounding areas, as well as clients Australia-wide.
GET A FREE CONSULTATION
Loan Point Solutions
Investment Loan Solutions Designed Around Your Goals
Whether you’re buying your first investment property, growing an existing portfolio or refinancing, choosing the right finance structure starts with understanding your circumstances and goals. We compare investment loan options from 30+ lenders and consider factors such as your deposit or available equity, income, existing commitments, repayment structure and loan features. Rather than focusing only on the advertised rate, we help you understand how different options may work for your situation and what their features and costs could mean over time. Whether you’re investing in Westmeadows, Broadmeadows or Craigieburn, elsewhere in Melbourne or across Australia, we can help you explore suitable lending options and understand the finance involved before you commit to a property. Our focus is on helping you make an informed decision about the loan, while recognising that property investment involves its own risks and that lending outcomes depend on your circumstances and the lender’s criteria. We keep the discussion practical and focused on your loan decisions.
Loan Point Solutions
How Lenders Assess an Investment Loan Application
Lenders assess investment loan applications based on more than the value of the property you want to purchase. They may consider your income, living expenses, existing home loans and other debts, credit history, deposit or available equity and the proposed investment property. Expected rental income may also be considered when assessing borrowing capacity, although lenders can apply different policies when deciding how much rental income they will recognise. Your overall financial position and the lender’s credit criteria can therefore affect the amount you may be able to borrow. At Loan Point Solutions, we take the time to understand your circumstances before comparing suitable options from our lender panel. Whether you’re considering an investment property in Coburg, Epping or surrounding Melbourne suburbs, or elsewhere across Australia, we help you understand what lenders may look at, what information may be required and how different loan options compare before you proceed. We explain differences between lender policies so you know what to expect.
Loan Point Solutions
Why Investors Choose Loan Point Solutions
Investors can have very different lending needs depending on whether they are purchasing their first investment property, refinancing an existing loan or preparing for another purchase. At Loan Point Solutions, we start by understanding your circumstances, existing commitments and objectives before comparing suitable options from our lender panel. We explain loan structures, features, rates and costs in straightforward language, helping you understand the differences rather than simply choosing a loan based on an advertised rate. We can also consider how a proposed investment loan may fit alongside your existing borrowing position and plans. Whether you’re investing in Essendon, Pascoe Vale or Moonee Ponds, elsewhere in Melbourne or across Australia, our aim is to provide clear information and credit assistance suited to your circumstances. We don’t promise property values, rental income or investment returns; we focus on the finance and help you make an informed lending decision. This means the conversation stays focused on your lending needs and circumstances.
Loan Point Solutions
Understanding the Costs of an Investment Loan
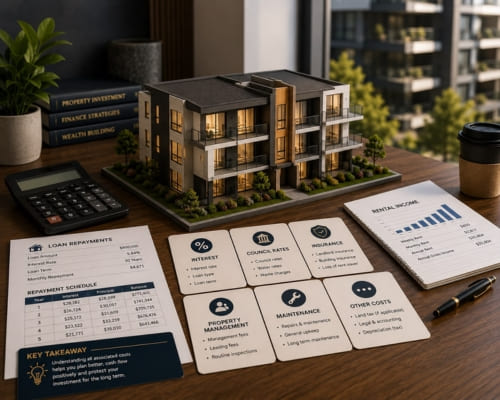
The cost of an investment property extends beyond the interest rate on the loan. Depending on the property and transaction, you may need to consider lender and valuation fees, conveyancing, government charges, insurance and other upfront expenses. Ongoing costs can include loan repayments, council rates, property management, maintenance, insurance and body corporate fees where applicable. Rental income may contribute towards these expenses, but it can vary and should not automatically be assumed to cover all property costs or loan repayments. At Loan Point Solutions, we help you understand the finance-related costs and repayment considerations associated with an investment loan, so you can assess the numbers before proceeding. Whether you’re considering an investment property in Sunbury, Craigieburn or elsewhere in Melbourne or across Australia, we can compare suitable loan options and explain their features and costs before you make a commitment. This helps you approach the lending decision with a clearer understanding of the financial commitments involved.
Loan Point Solutions
Interest Only, Principal & Interest or Using Your Equity?
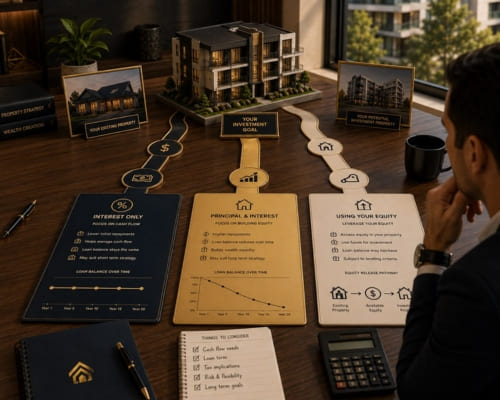
Investment borrowers can consider different loan structures depending on their circumstances, cash-flow preferences and longer-term plans. With an interest-only loan, repayments during the interest-only period generally cover the interest rather than reducing the principal, which can mean lower initial repayments but may result in higher repayments when the loan changes to principal and interest. A principal-and-interest loan includes repayments towards both interest and the amount borrowed, reducing the loan balance over time. Some investors may also consider using available equity in an existing property to help fund another purchase, subject to lender assessment and approval. Each approach has different costs, features and implications, so there is no single structure that will suit every investor. Whether you’re investing in Westmeadows, Moonee Ponds or elsewhere in Melbourne or across Australia, Loan Point Solutions can help you compare suitable structures and understand the potential benefits and trade-offs before choosing an option. We explain the differences clearly so you can weigh the options.
RELATED FINANCE SOLUTIONS
Explore our other lending solutions designed to support your property, investment and business goals
Build your property portfolio with the right finance.
For purchasing your first investment property, expanding an existing portfolio or using available equity, we compare suitable investment loan options based on your circumstances and goals.
Review your current loan and explore your options.
Whether you’re looking for a more competitive rate, better loan features or a different structure, we compare refinancing options and help you understand the potential benefits and costs of switching.
Finance your next business opportunity with confidence
From working capital and expansion to business purchases and other funding needs, we compare suitable finance options based on your business position and objectives.
TESTIMONIALS
What Our Investment Loans Customers Say About Us
The Process
3 Step Process For Your Investment Loans Needs
Strategy Call
Tell us your goal, income type and timeframe. We map your borrowing position honestly before you fall in love with a property.
We Structure
We match your income and deposit to the lenders whose policy actually fits, then package and submit the application properly the first time.
Through Settlement
You get updates at every milestone, not silence. We chase the lender, manage conditions, and stay with you after settlement for annual reviews.
Investment Loans In Westmeadows
FREQUENTLY ASKED QUESTIONS
Everything you need to know about our Investment Loans In Westmeadows
How much deposit do I need for an investment home loan?
Most lenders will look at investment lending up to 90 per cent of the property value with lenders mortgage insurance applying above 80 per cent, so a 10 per cent deposit plus costs is often the practical floor, and a 20 per cent deposit avoids the insurance entirely and opens up better pricing. The deposit does not have to be cash. A very common approach in Melbourne's north is to release equity from an existing home, using the available equity above the 80 per cent mark as the deposit for the investment purchase. You still need funds for transfer duty, which is not reduced for investors, plus conveyancing and inspections. We will model a cash deposit and an equity release side by side so you can see the difference in cost and in risk.
Can you borrow 100 per cent for an investment property?
Not as a single loan against the investment property alone. What people usually mean by a 100 per cent investment loan is a two-part structure: an equity release against a property you already own that covers the deposit and purchase costs, plus a separate loan of up to 80 per cent against the new property. The result is that no cash comes out of your pocket, but you are still borrowing against real security and both loans are assessed on your ability to service them. It is a legitimate and widely used structure. It also increases your total debt and your exposure if values move, so we model the servicing at a buffered rate before recommending it.
Does an investment loan cost me anything to arrange?
No, our service is paid by the lender on standard residential investment lending, in the same way as an owner-occupier loan. The costs that do apply are the lender's and the government's. Investment loans are commonly priced above owner-occupier loans, and interest-only lending is usually priced above principal and interest, so the structure you choose affects your holding cost. Package fees of roughly $250 to $400 a year are common where a rate discount applies, lender application and settlement fees range from nil to around $800, and transfer duty applies in full with no first home concession. Victorian land tax may also apply once your total land holdings pass the threshold, which is a question for your accountant rather than for us.
What is the difference between interest-only and principal and interest for an investor?
Interest-only means your repayments cover only the interest for an agreed period, commonly one to five years, which keeps your holding cost lower while you hold the property. Principal and interest reduces the balance from day one, costs more each month, and is generally priced more keenly. The trap with interest-only is the expiry. When the period ends, the loan reverts to principal and interest over the remaining term, so a 30-year loan with five years of interest-only repays the whole balance over the remaining 25 years, and the repayment step-up can be sharp. Interest-only also affects how some lenders assess your capacity for future purchases. We will show you both, with the expiry modelled, rather than defaulting to whichever carries the lower repayment today.
Why do you avoid cross-collateralising my home with the investment property?
Cross-collateralisation means the lender holds both properties as security for both loans, which is convenient for the lender and frequently unhelpful for you. It makes selling one property complicated, because the lender must reassess the whole position and may require the proceeds to reduce the remaining debt. It makes moving one loan to a different lender difficult without unwinding the entire structure. It also concentrates your whole portfolio with a single lender, so one change in their policy affects everything you own. We prefer standalone securities with a separate equity release where the numbers allow it, even when a lender pushes the other way. Occasionally cross-securing genuinely is the only way to make a purchase work, and if that is the case we will explain the trade-off rather than hide it.
My borrowing capacity dropped when I added the rental income. Why?
Because lenders do not count rental income at face value. Most apply a shading of around 20 per cent to allow for vacancy, management fees and maintenance, so $500 a week of rent may be assessed as roughly $400. At the same time, the new loan's repayment is assessed at a buffered rate well above the actual rate, and any existing investment debt is assessed the same way. The result is that the property adds less income than it adds liability, which is why capacity often falls rather than rises on the second or third purchase. The size of the shading and the treatment of existing debt varies between lenders, which is exactly why we test the file across several before choosing one. If your capacity has stalled, the lender may be the problem rather than your finances.
Request A Free Investment Loans Quote
GET A FREE CONSULTATION
BUSINESS
SERVICES
SERVICE AREAS
OPERATING HOURS
Sun: 9:00am - 9:00pm
Mon: 9:00am - 9:00pm
Tue: 9:00am - 9:00pm
Wed: 9:00am - 9:00pm
Thu: 9:00am - 9:00pm
Fri: 9:00am - 9:00pm
Sat: 9:00am - 9:00pm
CRN: 580515
ABN: 72 699 469 228