HOME LOANS
Home Loans
Made Simple.
The Right Loan for You.
We compare home loan options from 30+ lenders to find a solution suited to your goals and circumstances. Based in Melbourne's northern suburbs, we serve Westmeadows and surrounding areas, as well as clients Australia-wide.
GET A FREE CONSULTATION
Loan Point Solutions
Home Loan Solutions Designed Around You
Whether you're purchasing your first home, upgrading to a new property, refinancing an existing mortgage or building an investment portfolio, the right home loan structure can make a meaningful difference to your financial goals. At Loan Point Solutions, we help borrowers across Australia compare suitable home loan options from a broad panel of lenders, taking into account your income, deposit, borrowing capacity, existing commitments, property plans and longer-term objectives. Depending on your circumstances, we can assist with variable, fixed and split-rate home loans, offset and redraw facilities, low-deposit lending, refinancing, construction loans and bridging finance. We also work with a wide range of borrowers, including PAYG employees, self-employed professionals, contractors and applicants with more complex income structures. Whether you're purchasing a property in Westmeadows, Broadmeadows, Tullamarine, Gladstone Park, Craigieburn or surrounding northern Melbourne suburbs, or anywhere else across Australia, our focus is on helping you understand your options and choose a home loan solution appropriate for your circumstances.
Loan Point Solutions
Choosing the Right Lender for Your Circumstances
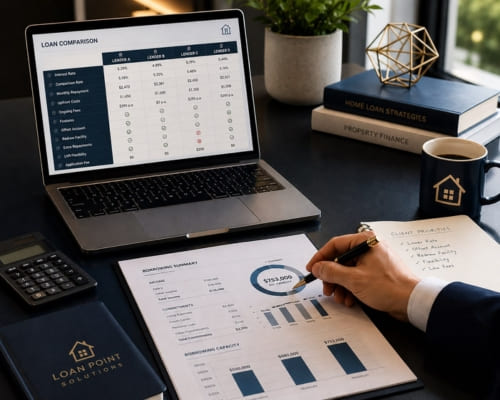
Choosing the right lender is about more than finding the lowest advertised interest rate. At Loan Point Solutions, we first understand your income, employment, deposit, existing commitments and borrowing objectives before comparing suitable lenders and loan options. We consider factors such as overtime, shift allowances, penalty rates, casual or contract income, second jobs and self-employed earnings, as lender policies can differ significantly in how these income sources are assessed. We also consider commitments such as credit cards, HECS-HELP and living expenses when assessing your potential borrowing capacity. Once we understand your position, we compare suitable options based on interest rates, comparison rates, fees, offset and redraw features and the overall suitability of the loan. This approach helps ensure your application is considered against lending criteria that align with your circumstances, giving you a more realistic understanding of your borrowing position before you commit to a property. Our service is available to borrowers across Australia, including clients throughout Westmeadows, Broadmeadows, Tullamarine, Airport West and surrounding northern Melbourne areas.
Loan Point Solutions
Why Choose Loan Point Solutions?
At Loan Point Solutions, we believe getting a home loan should be a clear and supported experience from your initial enquiry through to settlement and beyond. We keep you informed throughout the application process, explain your options in straightforward language and provide practical guidance when circumstances or requirements change. Our approach is personalised to your situation, whether you are a first home buyer, an existing homeowner, an investor, self-employed or managing a more complex income structure. Based in Melbourne's northern suburbs, we understand the needs of borrowers across Westmeadows and surrounding areas including Broadmeadows, Tullamarine, Gladstone Park, Craigieburn and Greenvale, while our service extends to clients Australia-wide. As your mortgage broker, we compare suitable loan options from our lender panel and help you understand the features, costs and requirements before making a decision. Our goal is to provide responsive communication, informed guidance and a lending solution that supports both your immediate property plans and longer-term financial goals.
Loan Point Solutions
Understanding the Costs of a Home Loan
Understanding the full cost of a home loan is just as important as finding a competitive interest rate. Our broker service is generally paid through lender commission arrangements, where applicable, and we explain any relevant fees or costs before you proceed. Depending on your circumstances and the loan you choose, costs may include lender application or settlement fees, annual package fees, valuation costs, lenders mortgage insurance (LMI) where applicable, government charges, mortgage registration, conveyancing and other property-related expenses. If you have a deposit below 20%, we can help you understand how LMI may affect the overall cost and compare potential options, including whether a different loan structure or deposit strategy may be more suitable. We also explain the difference between the interest rate and comparison rate, along with relevant fees and loan features, so you can assess the overall cost rather than focusing on the headline rate alone. Whether you're purchasing in Westmeadows or elsewhere in Melbourne's northern suburbs, or anywhere across Australia, our goal is to give you a clear understanding of the costs involved before you proceed.
Loan Point Solutions
Broker, Bank Branch or Comparison Site: Which Suits You
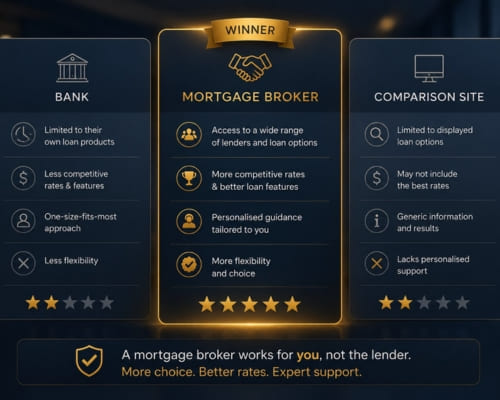
There is a case for each, and it depends on how straightforward your file is. Going direct to your own bank is genuinely simplest when your income is a single PAYG salary, your deposit is over 20 per cent, and you already hold a strong relationship with that bank, since there is only one policy to satisfy and no comparison to run. A comparison website is useful for seeing what advertised pricing looks like across the market, though it shows advertised rates rather than what you will actually be approved for, and it cannot tell you which lender will accept your overtime. A broker earns their place the moment the file has a complication: variable income, a short trading history, a low deposit, a tight finance clause, a guarantor, or more than one property. If your situation is genuinely simple, we will tell you so. If it is not, the value is in the policy match, not the rate. Call 0485 011 020 and we will tell you honestly which of the three fits you.
RELATED FINANCE SOLUTIONS
Explore our other lending solutions designed to support your property, investment and business goals
Build your property portfolio with the right finance.
For purchasing your first investment property, expanding an existing portfolio or using available equity, we compare suitable investment loan options based on your circumstances and goals.
Review your current loan and explore your options.
Whether you’re looking for a more competitive rate, better loan features or a different structure, we compare refinancing options and help you understand the potential benefits and costs of switching.
Finance your next business opportunity with confidence
From working capital and expansion to business purchases and other funding needs, we compare suitable finance options based on your business position and objectives.
TESTIMONIALS
What Our Home Loans Customers Say About Us
The Process
3 Step Process For Your Home Loans Needs
Strategy Call
Tell us your goal, income type and timeframe. We map your borrowing position honestly before you fall in love with a property.
We Structure
We match your income and deposit to the lenders whose policy actually fits, then package and submit the application properly the first time.
Through Settlement
You get updates at every milestone, not silence. We chase the lender, manage conditions, and stay with you after settlement for annual reviews.
Home Loans In Westmeadows
FREQUENTLY ASKED QUESTIONS
Everything you need to know about our Home Loans In Westmeadows
What salary do you need for a $500,000 loan?
There is no single salary figure, because lenders assess your income against your commitments, dependants and living expenses rather than in isolation. As a rough guide, a single applicant with no dependants and no other debts is often assessed for a loan of around five to six times gross income, so a $500,000 loan commonly sits in the range of a $85,000 to $110,000 gross income, though that is indicative only. What moves the number most is not salary at all but HECS-HELP debt, credit card limits (assessed on the limit, not the balance), car finance, childcare costs and how much of any overtime or bonus income a particular lender is willing to count. Lenders are also required to assess you at a buffer above the actual rate, so your assessed repayment is higher than your real one. Send us your payslips and we will run the actual calculators rather than a rule of thumb.
What would the repayments be on a $400,000 mortgage?
We can only answer this with the assumptions stated, because repayments depend entirely on the rate, the term and the repayment type, and rates change. As a worked illustration: a $400,000 loan on a 30-year term, principal and interest, at an annual rate of 6.00 per cent works out at roughly $2,400 a month. At 6.50 per cent the same loan is roughly $2,530 a month, and at 7.00 per cent roughly $2,660. Those figures exclude fees, insurance, rates and any lenders mortgage insurance, and they are an illustration rather than a quote or an offer. Your actual rate depends on the lender, your loan-to-value ratio and the product, so ask us for a comparison rate and the full conditions before you rely on any number.
Does using Loan Point Solutions cost me anything?
For a standard residential home loan, no. The lender pays us an upfront commission once your loan settles, typically in the order of 0.65 per cent of the loan amount plus GST, along with a smaller ongoing trail commission of roughly 0.15 to 0.20 per cent a year plus GST. Those figures are industry norms rather than a fixed schedule, and they are paid by the lender, not added to your loan or your rate. If a fee-for-service ever does apply, which happens on some commercial and complex facilities rather than standard home loans, we tell you the amount in writing before any work begins. You are never charged something you have not agreed to in advance.
How long does it take to go from pre-approval to settlement?
Pre-approval usually takes a few business days to two weeks depending on the lender's assessment queue and how complete the documents are when they go in. Once you have a signed contract, formal approval commonly takes one to two weeks, and settlement is then set by the contract itself, most often 30, 60 or 90 days in Victoria. The step that catches people out is the standard Victorian finance clause, which is frequently only 14 days, and lender queues do not pause for it. If your contract has a finance clause, tell us the date the moment you sign, because an extension has to be requested through your conveyancer before the clause lapses, not after.
How do you decide which lender to recommend?
Policy first, then price. We start by identifying which lenders will actually accept your income type in full, because that is where applications are won or lost. A lender that counts all of your shift allowance and only half of your overtime will reach a very different figure from one that does the reverse. Once we have the lenders whose policy genuinely fits, we compare them on rate and comparison rate, ongoing and upfront fees, offset and redraw features, and how long they are currently taking to assess. We then explain the shortlist and the trade-offs to you and you choose. As a credit representative, we are bound by the Best Interests Duty under Australian credit law, which means the recommendation has to serve your interests, not the lender's.
What happens if the valuation comes in below the price I paid?
It happens more often than people expect, particularly on off-the-plan purchases and in fast-moving auction markets, and it does not automatically end the purchase. The lender lends against the lower of the contract price and the valuation, so a shortfall means you need to cover the gap with additional deposit, accept a higher loan-to-value ratio and the lenders mortgage insurance that comes with it, or move the application to a lender using a different valuer. Ordering a second valuation with another lender is a genuine option and we do it regularly. The important thing is to raise it immediately rather than at the end of the finance clause, because your options narrow as the deadline approaches.
Request A Free Home Loans Quote
GET A FREE CONSULTATION
BUSINESS
SERVICES
SERVICE AREAS
OPERATING HOURS
Sun: 9:00am - 9:00pm
Mon: 9:00am - 9:00pm
Tue: 9:00am - 9:00pm
Wed: 9:00am - 9:00pm
Thu: 9:00am - 9:00pm
Fri: 9:00am - 9:00pm
Sat: 9:00am - 9:00pm
CRN: 580515
ABN: 72 699 469 228