First Home Buyer Loans in Westmeadows
From First Home Dream
to Homeowner
Your first home starts with the right loan.
We help first home buyers understand their options, compare suitable lenders and find a home loan solution that fits their deposit, income and circumstances. Based in Melbourne, we serve Westmeadows and surrounding areas, as well as clients Australia-wide.
GET A FREE CONSULTATION
Loan Point Solutions
What First Home Buyers Can Access
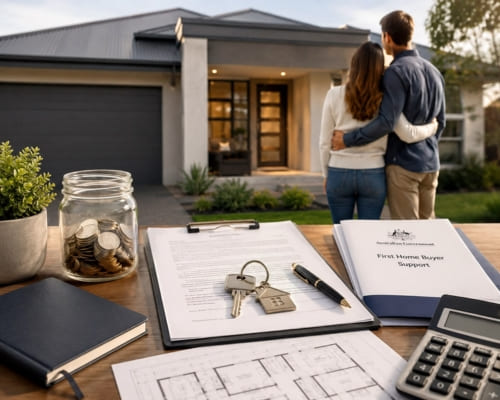
For eligible first home buyers, several government initiatives may help make buying a home more achievable. In Victoria, eligible buyers can receive a full land transfer duty exemption on homes valued up to $600,000, with a reduced amount of duty available for homes valued between $600,001 and $750,000. Eligible buyers purchasing a new home valued up to $750,000 may also qualify for the $10,000 First Home Owner Grant. The Australian Government 5% Deposit Scheme may allow eligible first home buyers to purchase with a minimum 5% deposit without Lenders Mortgage Insurance, subject to the scheme’s requirements and applicable property price caps. At Loan Point Solutions, we help first home buyers understand which options may apply to their circumstances, whether you’re purchasing in Westmeadows, Broadmeadows or Craigieburn, or elsewhere across Australia.
Loan Point Solutions
How We Assess Your First Home Loan Eligibility
Your eligibility for a first home loan depends on more than the size of your deposit. We consider your income, employment, living expenses, existing debts, credit commitments, savings history, deposit and the property you intend to purchase. Lender policies can differ when assessing casual, overtime, commission, contract or self-employed income, so understanding your borrowing position early can help you set a realistic property budget. We also consider whether relevant first home buyer assistance or low-deposit options may apply, while recognising that government scheme eligibility and lender approval are separate requirements. At Loan Point Solutions, we help you understand your borrowing position, compare suitable lenders and prepare for the application process, whether you’re buying in Coburg, Epping or surrounding Melbourne suburbs, or elsewhere across Australia.
Loan Point Solutions
Why First Home Buyers Choose Loan Point Solutions
Buying your first home can feel overwhelming when you’re trying to understand deposits, borrowing capacity, lender requirements and the costs involved. At Loan Point Solutions, we simplify the process by understanding your circumstances, explaining your options clearly and comparing suitable home loan solutions from our lender panel. We help you understand how your income, savings, expenses and existing commitments may affect your borrowing position, while considering relevant first home buyer assistance where applicable. For buyers in Essendon, Pascoe Vale and Westmeadows, our local presence provides a convenient point of contact, while our mortgage broking service is available to eligible borrowers Australia-wide. From your initial enquiry through to settlement, our goal is to provide practical guidance, clear communication and greater confidence as you take your first step into the property market.
Loan Point Solutions
Understanding the Costs of Buying Your First Home
Buying your first home involves more than saving a deposit. Alongside the purchase price and home loan, you may need to budget for costs such as conveyancing or legal fees, property inspections, lender fees, valuation costs, government charges and other expenses associated with purchasing a property. Eligible Victorian first home buyers may benefit from land transfer duty exemptions or concessions, while eligible buyers of qualifying new homes may also be able to access the First Home Owner Grant. At Loan Point Solutions, we help you understand the potential costs involved and how they may affect your deposit, borrowing capacity and overall budget. Whether you’re purchasing in Moonee Ponds, Sunbury or elsewhere in Melbourne, or across Australia, our aim is to help you understand the numbers before you commit to a property.
Loan Point Solutions
Buying Established or New: Which Option Is Right for You?
Choosing between an established home and a new property can affect your purchase price, upfront costs, available assistance and the type of loan you may need. An established property can provide greater choice in location and allow you to see the home before purchasing, while a new home, house-and-land package or eligible off-the-plan purchase may offer different financial considerations and, in Victoria, may qualify for the First Home Owner Grant if the relevant requirements are met. The Australian Government 5% Deposit Scheme can be used for both new and existing homes, subject to eligibility and location-specific price caps. At Loan Point Solutions, we help first home buyers compare deposit requirements, borrowing capacity, loan structure and upfront costs so you can understand which option may suit your circumstances and goals, whether you’re purchasing in Craigieburn, Epping or surrounding areas, or elsewhere across Australia.
RELATED FINANCE SOLUTIONS
Explore our other lending solutions designed to support your property, investment and business goals
Build your property portfolio with the right finance.
For purchasing your first investment property, expanding an existing portfolio or using available equity, we compare suitable investment loan options based on your circumstances and goals.
Review your current loan and explore your options.
Whether you’re looking for a more competitive rate, better loan features or a different structure, we compare refinancing options and help you understand the potential benefits and costs of switching.
Finance your next business opportunity with confidence
From working capital and expansion to business purchases and other funding needs, we compare suitable finance options based on your business position and objectives.
TESTIMONIALS
What Our First Home Buyer Loans Customers Say About Us
The Process
3 Step Process For Your First Home Buyer Loans Needs
Strategy Call
Tell us your goal, income type and timeframe. We map your borrowing position honestly before you fall in love with a property.
We Structure
We match your income and deposit to the lenders whose policy actually fits, then package and submit the application properly the first time.
Through Settlement
You get updates at every milestone, not silence. We chase the lender, manage conditions, and stay with you after settlement for annual reviews.
First Home Buyer Loans In Westmeadows
FREQUENTLY ASKED QUESTIONS
Everything you need to know about our First Home Buyer Loans In Westmeadows
What first home buyer support is available in Victoria?
There are three separate things and they are often confused. The First Home Guarantee is a federal scheme administered through Housing Australia that lets eligible buyers purchase with as little as a 5 per cent deposit without paying lenders mortgage insurance, subject to place availability, income tests and property price caps. The First Home Owner Grant is a Victorian payment available for new homes only, not established ones. Separately, the Victorian first home buyer duty exemption removes transfer duty on eligible purchases up to $600,000, with a concession that tapers away up to $750,000. Thresholds, caps and eligibility rules are set by government and change from time to time, so we confirm the current position with the State Revenue Office and Housing Australia for your purchase rather than relying on last year's figures.
What counts as genuine savings if my deposit was a gift from family?
Most lenders want to see that at least 5 per cent of the purchase price has been genuinely saved, which usually means accumulated in your own account over at least three months, and some will also accept consistent rent payments as an equivalent. A gifted deposit from a parent is very common in Melbourne's north and it is not a problem in itself, but the lender will normally want a signed gift letter confirming it is a gift rather than a loan, and some lenders will require it to have been held in your account for a period before settlement. Where the whole deposit is a gift and there are no genuine savings, the field of lenders narrows but does not disappear. Tell us how the deposit came together at the start, because it changes which lenders we approach.
How much deposit do I actually need to buy in Melbourne's north?
It depends which route you take, and the honest answer is a range. With a 20 per cent deposit you avoid lenders mortgage insurance entirely and get the widest choice of lenders and pricing. With 5 per cent through the First Home Guarantee you avoid lenders mortgage insurance as well, but places are limited and price caps apply. Outside those schemes, most lenders will lend up to 95 per cent of the value including capitalised lenders mortgage insurance, meaning a 5 per cent deposit plus costs, but the insurance premium then sits on top of your loan. Beyond the deposit itself you need funds for transfer duty where it applies, conveyancing, building and pest inspection, and moving costs. We model the options side by side so you can see what each one costs you over the life of the loan.
How long does the process take for a first home buyer?
Allow two to four weeks from your first conversation to a pre-approval in hand, assuming your documents are ready. Getting the documents right is what determines the timeline more than anything else, and expired payslips or bank statements are the single most common cause of a file stalling. A pre-approval typically lasts three months and can usually be extended with updated payslips. After that, the clock is set by your contract: formal approval commonly takes one to two weeks once a property is chosen, and settlement is normally 30 to 90 days. Start early, because pre-approval in place before you bid is what allows you to compete at a Saturday auction rather than watch one.
Do you charge first home buyers a fee?
No. On a standard residential first home loan the lender pays our commission at settlement and there is no charge to you. That includes the work involved in scheme applications, which can be substantial. Preparing a First Home Guarantee application, lodging the duty exemption paperwork correctly through your conveyancer, and coordinating a First Home Owner Grant application on a new build all take time, and none of it attracts an extra fee from us. If your situation ever moves into territory where a fee would apply, which is very unusual for a first home purchase, you would be told the amount in writing before any work started.
What happens if my pre-approval expires before I find a property?
This is extremely common and it is fixable, but it needs handling before you bid rather than after. Pre-approvals generally run for three months and can be refreshed with updated payslips and bank statements, and in most cases the lender simply re-runs the assessment. What complicates it is a change in your circumstances during that window, such as a new car loan, a new credit card, a change of employer, or a shift from permanent to casual work. Any of those can reduce your borrowing capacity, sometimes significantly. Tell us before you take on any new debt while you are house hunting, because an approved buyer can become an unapproved one over a single finance contract.
Request A Free First Home Buyer Loans Quote
GET A FREE CONSULTATION
BUSINESS
SERVICES
SERVICE AREAS
OPERATING HOURS
Sun: 9:00am - 9:00pm
Mon: 9:00am - 9:00pm
Tue: 9:00am - 9:00pm
Wed: 9:00am - 9:00pm
Thu: 9:00am - 9:00pm
Fri: 9:00am - 9:00pm
Sat: 9:00am - 9:00pm
CRN: 580515
ABN: 72 699 469 228