SMSF Loans in Westmeadows
Explore Property Finance Options
For Your SMSF.
Finance Your SMSF Property Plans With Clarity.
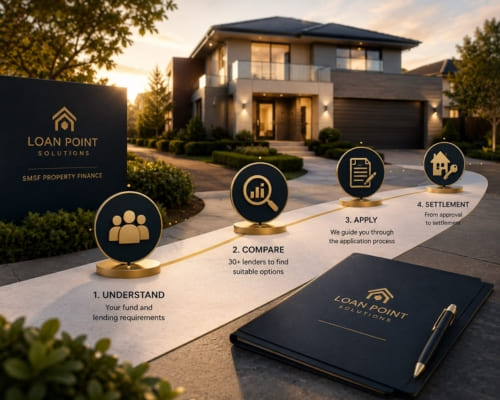
Explore suitable SMSF property finance options from 30+ lenders, based on your fund structure, financial position and lending requirements. Based in Melbourne, we assist clients across Melbourne and Australia-wide.
GET A FREE CONSULTATION
Loan Point Solutions
What an SMSF Loan Is and How It Is Structured
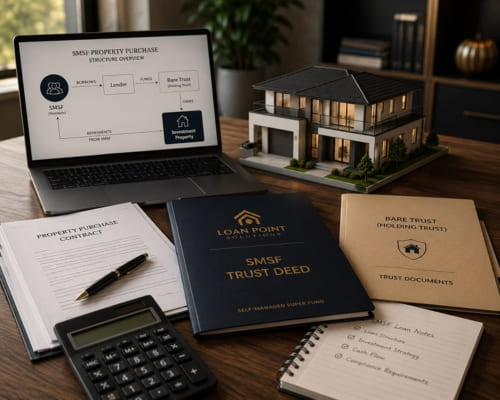
An SMSF loan is a specialised borrowing arrangement that may allow an eligible self-managed super fund to acquire certain assets through a Limited Recourse Borrowing Arrangement (LRBA). Under an LRBA, borrowed funds are generally used to acquire a single acquirable asset, with the asset held in a separate trust while the borrowing is in place. The structure must meet specific superannuation and lending requirements, so the fund structure, proposed property, investment strategy and loan arrangements need to be considered carefully. At Loan Point Solutions, we help trustees understand the lending structure, documentation and finance requirements involved in an SMSF property loan. We compare suitable options from 30+ lenders, where available, based on the proposed transaction and lending criteria. Whether you’re considering an SMSF property purchase in Westmeadows, Gladstone Park or Tullamarine, we assist clients across Melbourne and Australia-wide. Trustees should obtain appropriate professional advice before proceeding.
Loan Point Solutions
How Lenders Assess SMSF Loan Applications
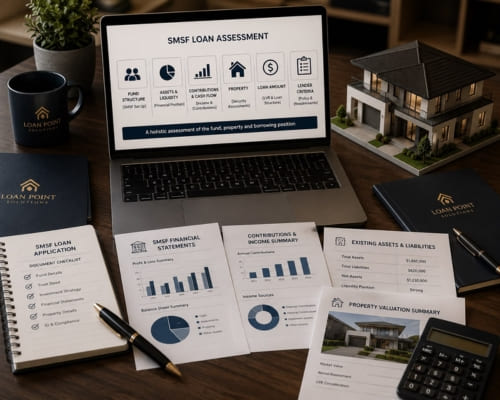
Lenders assess SMSF loan applications by looking at both the proposed property and the financial position of the fund. Depending on the lender, assessment may consider the fund’s assets, contributions, available liquidity, proposed loan amount, property type, rental income where applicable and the overall borrowing structure. Lender policies can also differ around loan-to-value ratios, acceptable securities, documentation and trustee requirements. At Loan Point Solutions, we help trustees understand these lending considerations before an application is submitted and compare suitable options from 30+ lenders, where applicable. Rather than focusing only on an advertised interest rate, we consider the proposed security, borrowing position, lender criteria and overall loan structure. Understanding these requirements early can help identify documentation issues and potential lending considerations before applying. Whether you’re based in Craigieburn, Greenvale or Roxburgh Park, we assist clients across Melbourne and Australia-wide with the lending process and help make the requirements easier to understand.
Loan Point Solutions
Why SMSF Trustees Choose to Work With Us
SMSF lending can involve different structures, lender policies and documentation requirements, making it important to understand the finance process before submitting an application. At Loan Point Solutions, we take the time to understand the proposed transaction, fund structure and lending requirements before comparing suitable options from 30+ lenders, where available. We can help trustees understand lender requirements, identify the information needed for an application and coordinate the finance process through to settlement. Our role is focused on the lending side of the transaction; we do not determine whether establishing an SMSF or investing in property through an SMSF is appropriate for you. Trustees should obtain independent accounting, legal and financial advice where required before proceeding. Whether you’re based in Essendon, Pascoe Vale or Moonee Ponds, we assist clients across Melbourne and Australia-wide. Our approach is designed to make the borrowing process clearer, while helping trustees understand the requirements associated with their proposed SMSF property loan.
Loan Point Solutions
What Are the Borrowing Costs to Establish and Run an SMSF Loan?
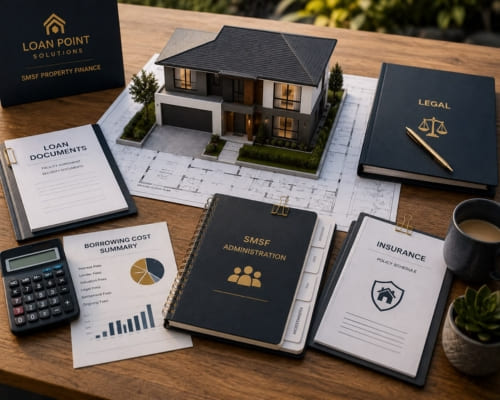
The cost of an SMSF property loan involves more than the interest rate. Depending on the transaction, costs may include lender application and settlement fees, valuation fees, legal and loan documentation costs, trust establishment or restructuring expenses and other costs associated with setting up the borrowing arrangement. The SMSF itself can also involve ongoing accounting, administration, audit, insurance and property-related expenses. These costs can vary depending on the fund, lender, loan structure and property, so they should be considered before proceeding. At Loan Point Solutions, we help trustees understand the finance-related costs associated with suitable lending options and identify the lender requirements that may affect the overall transaction. We do not provide accounting, tax or financial advice, so those aspects should be discussed with appropriately qualified professionals. Whether you’re considering an SMSF property loan in Broadmeadows, Sunbury or Mickleham, we assist clients across Melbourne and Australia-wide with the lending side of the process.
Loan Point Solutions
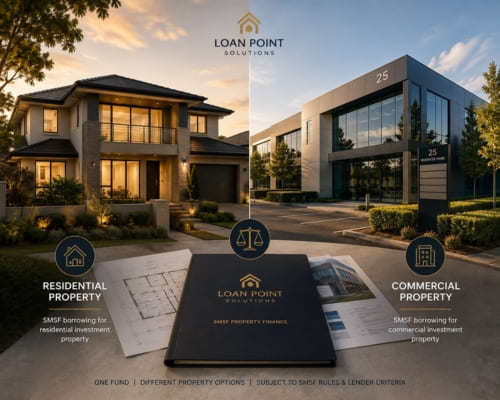
Residential or Commercial Property: What Can an SMSF Borrow For?
An eligible SMSF may be able to borrow to acquire certain residential or commercial property through an LRBA, provided the arrangement satisfies applicable superannuation and borrowing requirements. The property must meet the relevant investment rules, and additional restrictions can apply to how the property is acquired, used and dealt with. Residential property generally cannot be lived in or rented by fund members or related parties, while commercial property can involve different considerations depending on its use and the parties involved. At Loan Point Solutions, we help trustees understand the lending requirements associated with the proposed property and compare suitable finance options based on the security, loan structure and lender criteria. We can consider options from 30+ lenders, where available, rather than assuming residential or commercial lending will work the same way. Whether you’re considering property in Epping, Thomastown or Reservoir, we assist clients across Melbourne and Australia-wide. Appropriate SMSF, legal and financial advice should be obtained before proceeding.
RELATED FINANCE SOLUTIONS
We help first home buyers understand their options, compare suitable lenders and find a home loan solution that fits their deposit, income and circumstances. Based in Melbourne, we serve Westmeadows and surrounding areas, as well as clients Australia-wide.
We help you find a home loan that is suited to your financial circumstances and long-term goals. We consider your income, deposit, existing commitments and borrowing capacity before comparing suitable lending options. With access to a broad range of lenders, we can compare interest rates, loan features and structures to help you make an informed decision. Whether you are purchasing your first home, upgrading or refinancing, we provide clear guidance throughout the lending process, from application through to settlement.
Whether you’re buying your first investment property, growing your portfolio or refinancing, we compare 30+ lenders to find a loan suited to your goals and circumstances. Based in Melbourne, we serve Westmeadows and surrounding areas, as well as clients Australia-wide.
TESTIMONIALS
What Our SMSF Loans Customers Say About Us
The Process
3 Step Process For Your SMSF Loans Needs
Strategy Call
Tell us your goal, income type and timeframe. We map your borrowing position honestly before you fall in love with a property.
We Structure
We match your income and deposit to the lenders whose policy actually fits, then package and submit the application properly the first time.
Through Settlement
You get updates at every milestone, not silence. We chase the lender, manage conditions, and stay with you after settlement for annual reviews.
SMSF Loans In Westmeadows
FREQUENTLY ASKED QUESTIONS
Everything you need to know about our SMSF Loans In Westmeadows
Can an SMSF provide a loan?
Two different questions get asked here and they have different answers. An SMSF generally cannot lend money to a member or a related party of the fund, because that would breach the in-house asset and related-party rules under superannuation law. An SMSF can, however, borrow to buy an asset, provided the borrowing is structured as a limited recourse borrowing arrangement that meets the requirements of the SIS Act. In practice a member or related party can also lend to the fund under a related-party limited recourse arrangement, but it must be on arm's length commercial terms and the ATO publishes safe harbour terms for exactly this. All of that is territory for your accountant and adviser to confirm for your fund. Our role is arranging the borrowing once the structure is settled.
Which banks do SMSF loans?
The panel has narrowed considerably, and this is the single most important practical point. Most of the major banks withdrew from SMSF residential lending some years ago, and the market is now served largely by second-tier lenders, non-bank lenders and specialist funders, with a handful of banks still active in SMSF commercial. That means SMSF rates and fees generally sit above standard residential lending, and it also means the lender you bank with personally is probably not an option for your fund. We will not name specific lenders here because appetite and policy in this space change frequently, and quoting a stale panel helps nobody. Call us and we will tell you who is currently writing the type of deal you have.
What is the interest rate for SMSF loans?
We cannot responsibly quote a figure here, because SMSF pricing moves and varies widely by lender, property type and loan-to-value ratio, and any number we published would be out of date and could mislead you. What we can tell you is the structural reality: SMSF lending is consistently priced above standard residential lending, because the lender's recourse is limited to the single asset and the market is served by fewer lenders. Commercial SMSF lending is generally priced above residential SMSF. When we present options you will get the actual rate, the comparison rate and the full conditions in writing from the lender, so you can compare properly rather than relying on an advertised figure.
What does an SMSF loan cost to set up?
More than a standard loan, and most of the cost is not ours. The bare or holding trust has to be established and the deed prepared, which is typically done by your accountant or solicitor and commonly runs $1,500 to $3,000, and if a corporate trustee is set up for the holding trust there are ASIC registration costs on top. Lender application and establishment fees on SMSF lending are generally higher than residential, often several hundred to a couple of thousand dollars, and most lenders require an independent legal advice certificate for the trustees, adding further legal cost. A valuation is required as usual, and commercial valuations are considerably dearer than residential. Your accountant's fees for the additional fund administration are ongoing. These are indicative figures set by third parties and we confirm them for your structure.
Can you advise whether my super fund should buy a property?
No, and it is important to be clear about that boundary. Loan Point Solutions provides credit assistance, which means arranging and structuring the loan. Whether your self-managed super fund should borrow, whether property suits your fund's investment strategy, the tax consequences, and whether the fund has adequate liquidity and insurance are all financial and taxation advice, which sits with your licensed financial adviser and your accountant. What we will do is work alongside them, tell them exactly what the lender requires, model what the borrowing costs and what the servicing looks like, and flag anything in the loan structure that would create a compliance problem. Any broker who tells you a super fund should buy property without holding the relevant licence is operating outside their authorisation.
What is the single acquirable asset rule and how do people breach it?
Each limited recourse borrowing arrangement can only be used to acquire one single acquirable asset, and this trips people up more often than any other rule. A house on one title is one asset. Two adjoining titles are generally two assets and would need two separate arrangements, even if you think of them as one property. Off-the-plan apartments, subdividable blocks and properties spanning multiple titles all need care at contract stage. The related trap is the improvement rule: borrowed funds cannot be used to improve the asset in a way that changes its character. Repairing a roof is maintenance and generally fine; demolishing a house and building units is a change of character and is not permitted while the borrowing is in place. Get the contract checked before you sign, not after.
Request A Free SMSF Loans Quote
GET A FREE CONSULTATION
BUSINESS
SERVICES
SERVICE AREAS
OPERATING HOURS
Sun: 9:00am - 9:00pm
Mon: 9:00am - 9:00pm
Tue: 9:00am - 9:00pm
Wed: 9:00am - 9:00pm
Thu: 9:00am - 9:00pm
Fri: 9:00am - 9:00pm
Sat: 9:00am - 9:00pm
CRN: 580515
ABN: 72 699 469 228