REFINANCING
A Better Loan Starts With a Better Review.
Review Your Home Loan. Explore Your Options.
Whether you're looking to review your current loan, access equity or consolidate eligible debts, we compare options from 30+ lenders to help you explore suitable refinancing options. Based in Melbourne, we assist clients across Melbourne and Australia-wide.
GET A FREE CONSULTATION
Loan Point Solutions
Why People Choose to Refinance
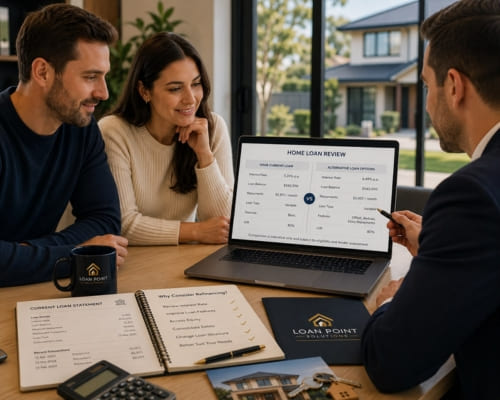
Refinancing can be worth considering when your current home loan no longer fits your circumstances or you want to review what is available in the market. Some homeowners refinance to seek a more suitable interest rate, change loan features, access available equity, consolidate eligible debts or move to a structure that better matches their needs. It is not always about getting a lower rate, and refinancing can involve costs that need to be considered alongside any potential benefit. At Loan Point Solutions, we start by understanding your current loan, financial position and goals before comparing suitable options from 30+ lenders. Whether you’re reviewing a home loan in Westmeadows, Broadmeadows or Craigieburn, elsewhere in Melbourne or across Australia, we can help you understand the options and costs involved. We explain the differences between suitable loans clearly, so you can decide whether refinancing may be appropriate for your circumstances rather than making a change simply because another rate is advertised.
Loan Point Solutions
How Does the Refinancing Process Actually Work?
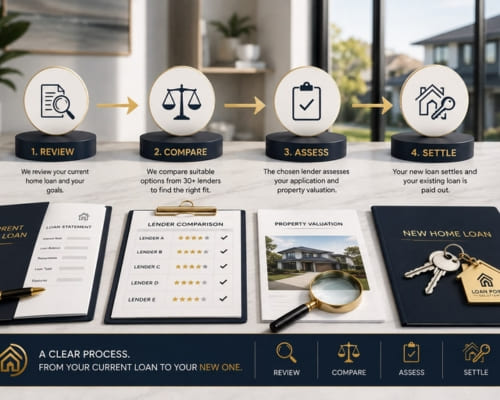
Refinancing generally involves replacing your existing home loan with a new loan, either with your current lender or another lender. The process usually starts with reviewing your current loan, financial position and what you want to achieve. We then compare suitable options, look at the relevant rates, features and costs, and help you understand how the new loan would work. If you decide to proceed, the new lender will assess your application and may require documents, a property valuation and other information before approval. Once approved, the new loan is arranged and the existing loan is discharged as part of the settlement process. Whether you’re refinancing in Coburg, Epping or surrounding Melbourne suburbs, or elsewhere across Australia, Loan Point Solutions can guide you through the process and explain what to expect at each stage. Timing and requirements can vary between lenders, so we help you understand the process before you commit to a particular option.
Loan Point Solutions
Why Homeowners Choose Loan Point Solutions for Refinancing
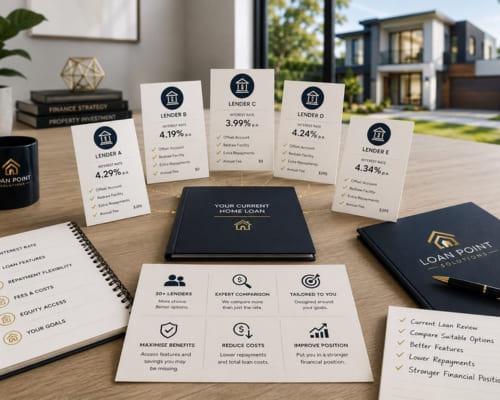
Refinancing is not simply about finding a different interest rate. At Loan Point Solutions, we first look at your existing loan, financial position and reasons for considering a change, then compare suitable options from our panel of 30+ lenders. We explain differences in rates, loan features, repayment structures, fees and other considerations so you can understand what you are comparing. We can also help you consider whether accessing available equity or consolidating eligible debts is appropriate for your circumstances. Whether you’re refinancing in Essendon, Pascoe Vale or Moonee Ponds, elsewhere in Melbourne or across Australia, we provide a clear and practical approach to reviewing your home loan. Our focus is on helping you make an informed lending decision based on your circumstances and priorities, rather than recommending a change simply because it appears cheaper at first glance. If your current loan still suits your needs, keeping it may also be worth considering.
Loan Point Solutions
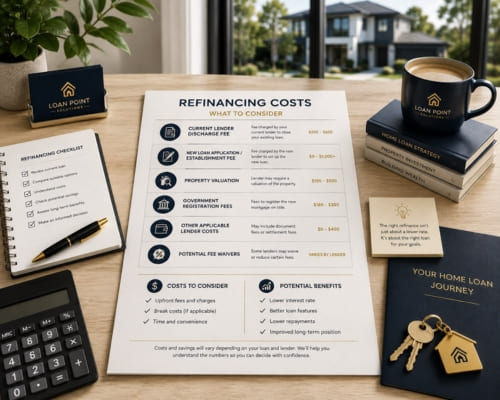
What Does Refinancing Cost? A Line-by-Line Look
The cost of refinancing can vary depending on your existing loan, the new lender, your property and the type of refinancing you are considering. Potential costs may include a discharge fee from your current lender, application or establishment fees, valuation costs, government registration fees and other charges that may apply to the new loan. There can also be costs associated with changing loan features or consolidating other debts. Some lenders may offer fee waivers or other incentives, but these should be considered alongside the overall cost and loan terms rather than viewed in isolation. Whether you’re refinancing a property in Sunbury, Craigieburn or elsewhere in Melbourne or across Australia, we help you identify the relevant costs and compare them with the potential benefits of changing loans. Understanding the full cost can help you assess whether refinancing is likely to make sense for your circumstances, rather than focusing only on the advertised interest rate.
Loan Point Solutions
Refinance or Leave Your Current Loan Alone?
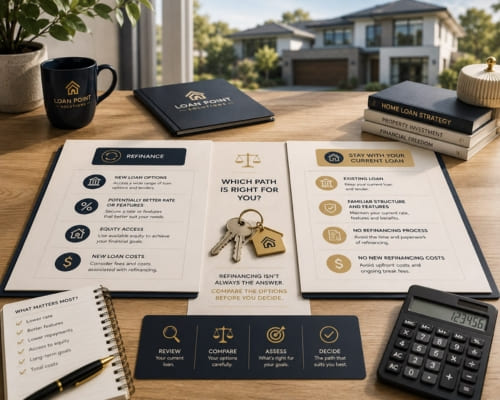
Refinancing is not automatically the right choice for every homeowner. A new loan may offer features or terms that better suit your circumstances, but changing loans can also involve upfront costs, a different repayment structure or other considerations. Before refinancing, it can be useful to compare the potential benefits of changing loans with the costs of leaving your existing loan. In some circumstances, staying with your current lender may remain a suitable option, particularly if the existing loan already meets your needs. Whether you’re considering refinancing in Westmeadows, Moonee Ponds or elsewhere in Melbourne or across Australia, Loan Point Solutions can help you compare the available options and understand the trade-offs. We look at your current loan, financial position, objectives and the costs involved before helping you assess the alternatives. The aim is not to refinance for the sake of changing loans, but to help you make an informed decision about what works for you.
RELATED FINANCE SOLUTIONS
Explore our other lending solutions designed to support your property, investment and business goals
Build your property portfolio with the right finance.
For purchasing your first investment property, expanding an existing portfolio or using available equity, we compare suitable investment loan options based on your circumstances and goals.
Review your current loan and explore your options.
Whether you’re looking for a more competitive rate, better loan features or a different structure, we compare refinancing options and help you understand the potential benefits and costs of switching.
Finance your next business opportunity with confidence
From working capital and expansion to business purchases and other funding needs, we compare suitable finance options based on your business position and objectives.
TESTIMONIALS
What Our Refinancing Customers Say About Us
The Process
3 Step Process For Your Refinancing Needs
Strategy Call
Tell us your goal, income type and timeframe. We map your borrowing position honestly before you fall in love with a property.
We Structure
We match your income and deposit to the lenders whose policy actually fits, then package and submit the application properly the first time.
Through Settlement
You get updates at every milestone, not silence. We chase the lender, manage conditions, and stay with you after settlement for annual reviews.
Refinancing In Westmeadows
FREQUENTLY ASKED QUESTIONS
Everything you need to know about our Refinancing In Westmeadows
Is it worth refinancing a home loan?
Sometimes, and sometimes not, which is the honest answer most sites avoid. It is usually worth investigating if you are rolling off a fixed rate, if your loan has been with the same lender for more than two years without a review, if your property value has risen enough to push you below the 80 per cent loan-to-value mark, or if you are carrying higher-cost debt that could be consolidated. It is often not worth it if you have a small remaining balance, if you are already at a competitive rate, if you would trigger fixed-rate break costs, or if your income or employment has changed in a way that would make a new assessment harder than your current position. We run the comparison including every switching cost and tell you the answer either way, including when the answer is to stay.
How much does it cost to refinance a mortgage?
The costs are mostly small and predictable. Your existing lender charges a discharge fee, commonly in the range of $300 to $400, and there are state mortgage discharge and registration fees of roughly $100 to $200 each in Victoria. The incoming lender may charge an application or settlement fee anywhere from nil on a fee-free product up to around $800, and a valuation may be free or in the order of $200 to $400. As a rough total, a straightforward refinance commonly costs somewhere between $500 and $1,500. The exception is a fixed loan, where break costs are calculated by the lender based on movements in wholesale rates and can run into thousands, so those must be quoted by your lender before any decision. If your loan-to-value ratio is above 80 per cent, lenders mortgage insurance may also apply again with the new lender and is not transferable.
How long does a refinance take from start to settlement?
Typically four to six weeks, though it varies with the outgoing lender more than the incoming one. The application and approval usually run one to two weeks with complete documents, and the valuation happens in parallel. The step that consistently takes longest is the discharge, because your existing lender has to process a discharge authority form, and those queues can run two to three weeks on their own. The practical lesson is to lodge the discharge authority as soon as you have formal approval rather than waiting for the new lender to request it. We handle that sequencing for you and give you an update at each stage.
Can I consolidate credit cards and a car loan into my home loan?
Usually yes, provided you have the equity and the lender is satisfied with the reason. The benefit is real and immediate, because unsecured debt generally carries a much higher rate than home lending, so consolidating typically cuts your total monthly outgoings noticeably. The catch that nobody mentions is the term. Moving a five-year car loan into a 30-year mortgage lowers the monthly payment but can increase the total interest paid over the life of the debt unless you deliberately keep repaying at the old level. We usually recommend consolidating into a split, so the consolidated portion sits on a shorter term rather than being absorbed into a 30-year balance. Some lenders also want evidence the underlying spending pattern has changed before approving.
How do I know you are not just moving me to earn a commission?
It is a fair question and the safeguard is built into the law. As a credit representative, we operate under the Best Interests Duty, which legally requires the recommendation to serve your interests. There is also a practical safeguard: brokers face a clawback if a loan is refinanced away within roughly the first two years, so churning clients between lenders works against us financially. In practice, the first thing we do on a refinance enquiry is contact your existing lender and request a repricing on your behalf, which costs you nothing and quite often solves the problem without a switch. If we recommend moving, we show you the full cost comparison and the reasoning in writing.
My fixed rate is expiring. What should I do and when?
Start about 60 to 90 days before the expiry date, not after it. When a fixed period ends, most loans automatically revert to that lender's standard variable rate, which is frequently well above what the same lender offers new customers, and it can happen without a phone call. Starting early gives you time to request a repricing from your existing lender, get a valuation done if your property value has moved, and complete a refinance before the reversion takes effect if the numbers justify it. Breaking a fixed loan before expiry is a different matter and can carry substantial break costs calculated on wholesale rate movements, so we always request that figure from the lender before considering it.
Request A Free Refinancing Quote
GET A FREE CONSULTATION
BUSINESS
SERVICES
SERVICE AREAS
OPERATING HOURS
Sun: 9:00am - 9:00pm
Mon: 9:00am - 9:00pm
Tue: 9:00am - 9:00pm
Wed: 9:00am - 9:00pm
Thu: 9:00am - 9:00pm
Fri: 9:00am - 9:00pm
Sat: 9:00am - 9:00pm
CRN: 580515
ABN: 72 699 469 228